Life insurance death benefits paid to a beneficiary after a death are generally not subject to federal income tax. Certain related amounts, such as interest paid on the proceeds or cash surrender value above the policy's cost basis, can be taxable. This guide explains key points for beneficiaries and executors to be aware of, including: when proceeds are taxable, how interest and cash value are taxed, employer-paid group coverage, federal estate taxes, and more.
Key Takeaways
- Life insurance death benefits are generally free from federal income tax.
- Interest paid on life insurance proceeds is taxable and may appear on Form 1099-INT.
- Cash surrender proceeds above the policy's adjusted cost basis are taxable.
- Life insurance can count toward the taxable estate; state estate or inheritance taxes may apply.
- Elayne uses document analysis and the NAIC locator to search for forgotten life insurance policies.
The Default Rule: Life Insurance Death Benefits Are Generally Not Taxable
Life insurance death benefits are generally free from federal income tax.
A standard lump-sum death benefit usually requires no federal income tax set-aside for beneficiaries who file a life insurance claim. Exceptions can depend on the policy’s history and whether the payout includes amounts beyond the death benefit.
{{blog-cta-financial}}
When Life Insurance Proceeds Can Become Taxable
Interest on proceeds held by the insurer is taxable, including interest paid with installments. That interest is counted as income on the beneficiary's tax return.
Other situations can also affect how proceeds are taxed. For example:
- A policy transferred for money or other value can lose part of its income-tax exclusion, subject to exceptions.
- When the estate receives proceeds, interest can become estate income. Insurance can also count toward the federal taxable estate calculation.
Taxes on Cash Value: Withdrawals, Loans, and Surrenders
Accessing whole life cash value can create taxable income. Cost basis generally means premiums paid, adjusted for refunds and other amounts.
- Withdrawals above basis are generally taxable.
- Policy loans generally avoid immediate tax, but a lapse with an outstanding loan can trigger income. Modified endowment contracts have different rules.
- Full surrender proceeds above basis are taxable, with Form 1099-R reporting under IRS cash surrender rules.
The policy’s history affects taxable income, so the cash received may not show the full tax exposure.
Employer-Paid Group Life Insurance and Taxes
Employer-paid group term life insurance generally provides an income-tax-free death benefit to beneficiaries. Because the employer pays the premiums instead of the employee, the coverage is an employment benefit subject to separate tax rules. The employee’s tax treatment during life is separate:
- Under IRC Section 79, the first $50,000 of coverage is generally excluded from employee income.
- Above that threshold, the calculated coverage cost counts as taxable pay, called “imputed income,” despite no cash payment. Age-based IRS Premium Table rates determine the cost, subject to federal income, Social Security, and Medicare taxes.
An IRS worked example shows how the coverage exclusion applies when both basic and optional coverage are considered carried by the employer:
| Part of the Example | Amount or Treatment |
|---|---|
| Basic coverage | $40,000 |
| Optional coverage | $100,000 |
| Coverage exclusion | $50,000 |
| Optional coverage within the exclusion | $10,000 |
| Optional coverage above the exclusion | $90,000; its calculated coverage cost is included in income, not the coverage amount itself. |
The coverage threshold does not cap the beneficiary’s death benefit exclusion.
Estate Taxes and Life Insurance: When the Policy Becomes Part of the Taxable Estate
Federal estate tax is separate from income tax. Life insurance proceeds can enter the gross estate if the insured retained rights such as changing beneficiaries, called “incidents of ownership,” which is relevant to understanding the federal estate tax exemption.
The 2026 federal estate tax exemptions are:
| Individual | Married couple |
|---|---|
| $15 million | $30 million combined |
Fidelity’s estate tax guidance explains how a deceased spouse’s unused exemption can transfer to a surviving spouse when the deceased spouse’s executor files a timely estate tax return.
The Spousal Exception: Life Insurance Payouts to a Surviving Spouse
Life insurance proceeds paid directly to a surviving spouse who is a U.S. citizen generally qualify for the unlimited marital deduction. This allows proceeds to pass without federal estate tax, but does not shield that money from estate tax when the surviving spouse later dies.
The death benefit itself is generally income-tax-free, as it is for other beneficiaries. Different marital-deduction rules apply to noncitizen spouses and may require specialized tax advice from a qualified professional.
{{blog-cta-financial}}
How Elayne Supports Families Handling Life Insurance After a Death
Elayne is an online operating layer for settling an estate after a death. For life insurance, its Verified Asset Search looks for policies that may not appear in the paperwork, and its shared estate record keeps claim documents and related tax records in one place.
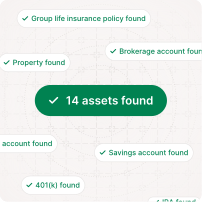
Verified Asset Search uses document analysis, the NAIC life insurance locator, and database queries to look for forgotten life insurance policies and dormant accounts. Document analysis reviews tax returns, bank statements, and other records for clues, such as recurring premium payments or interest and dividend income, that point to the institution holding an asset.
The NAIC locator is a free service of the National Association of Insurance Commissioners. A request goes to participating insurers, and an insurer that finds a matching policy contacts the named beneficiary. State unclaimed property registries are also searched, since proceeds can be reported to a state when an insurer cannot reach a beneficiary.
Locating a policy is a separate step from claiming it. A claim is submitted to the insurer after a policy is located, and payment timelines after submission vary by insurer and by state.
Authority over life insurance depends on how the policy is set up. A named beneficiary is the person entitled to claim the death benefit from the insurer. When the estate is the beneficiary, the executor or personal representative, whose authority comes from a court appointment such as Letters Testamentary, acts for the estate.
Elayne applies the same principle to its own access. Deeper levels of Verified Asset Search unlock only after the right person is verified at the right stage, and the shared estate record uses role-based permissions so executors, authorized family members, and attorneys each see only what their assigned role allows.
Insurers generally ask for a claim form and a certified copy of the death certificate, though requirements differ by company. Elayne guides families through the documentation a life insurance claim involves, and policy documents, beneficiary details, insurer payment statements, and tax forms are kept together in the shared estate record.
Statements that separate the death benefit from interest show what is reportable. Interest on proceeds held by an insurer is taxable and may be reported on Form 1099-INT, while the death benefit itself is generally not subject to federal income tax. A tax professional can use the same record to review the figures.
Life insurance is often one of several assets passing to beneficiaries at the same time. Elayne tracks the distribution deadlines that apply to inherited retirement accounts, including annual required minimum distributions in 2026 for certain beneficiaries, and maps who inherits each asset and how it transfers.
In summary, a life insurance payout after a death involves four key questions: whether a policy exists, who is entitled to claim it, which documents the insurer requires, and which parts of the payout carry tax consequences. Elayne organizes each question in one estate record, with access set by each person’s role.
FAQ
If a life insurance payout skips probate, can the IRS still count it for estate tax?
Yes. A payout to a named beneficiary can bypass probate yet still count toward the insured person’s federal gross estate if they retained ownership rights over the policy. Probate determines how assets transfer; estate-tax rules determine which assets count for tax purposes.
How are life insurance records organized in Elayne for a tax professional?
Policy documents, beneficiary details, insurer payment statements, and any tax forms can be kept together in Elayne’s shared estate record. Statements separating the death benefit from interest help a tax professional determine what is reportable, while ownership records help clarify potential estate-tax treatment.
Is a life insurance death benefit taxable?
A death benefit paid to a named beneficiary is generally not subject to federal income tax. The exclusion comes from Section 101(a) of the Internal Revenue Code. Amounts paid beyond the death benefit, such as interest, can be taxable. Federal estate tax is a separate tax that can apply to the estate of the person who died.
Is interest on life insurance proceeds taxable, and how is it reported?
Yes. Interest earned on proceeds that an insurer holds after a death is taxable income to the person who receives it. This includes the interest portion of installment payments, while the death benefit portion of each installment remains excluded. Insurers generally report interest of $10 or more on Form 1099-INT.
Do beneficiaries receive a 1099 for life insurance proceeds?
A lump-sum death benefit typically arrives without a Form 1099. Form 1099-INT can be issued for interest paid on proceeds. Form 1099-R generally goes to a policyholder after a taxable surrender or distribution from a policy. A tax form does not automatically mean the entire payout is taxable, because the amount received can differ from the amount subject to income tax.
*Disclaimer: This article is for informational purposes only and does not provide legal, medical, financial, or tax advice. Please consult with a licensed professional to address your specific situation.