After the owner of an IRA dies, the beneficiary who inherits the account may be required to take withdrawals called required minimum distributions (RMDs). Whether withdrawals are required, and how much, depends on the beneficiary's relationship to the person who died, the date of death, and whether the owner had reached their required beginning date. This guide explains key points for beneficiaries and families to be aware of, including: which rules apply to each type of beneficiary, how the 10-year rule works, calculating an RMD with the IRS Single Life Expectancy Table, accounts that inherited before 2020, and more.
Key Takeaways
- Inherited IRA RMD rules depend on beneficiary status, death date, and the owner's RMD start date.
- Most non-spouse heirs under post-2019 rules face a 10-year deadline; annual RMDs may also apply.
- Life expectancy RMDs equal the prior December 31 balance divided by the applicable IRS factor.
- Missed RMDs face a 25% tax, reduced to 10% if corrected within the allowed window.
- Elayne tracks inherited IRA deadlines; beneficiaries remain responsible for distributions.
Three Factors That Determine a Beneficiary’s RMD Requirement
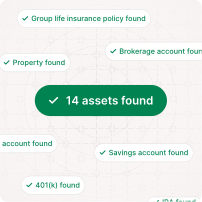
Before these factors can be applied, beneficiaries typically need to find bank and investment accounts tied to the inherited IRA. The IRS identifies three beneficiary RMD factors:
- Relationship to the owner and beneficiary characteristics, such as disability or status as the owner’s minor child.
- Whether the owner died before, on, or after their required beginning date, when required withdrawals must begin.
- Whether death occurred before January 1, 2020, or on or after that date, when SECURE Act beneficiary changes apply.
These facts determine which inherited IRA RMD rules apply before calculating distributions.
{{blog-cta-financial}}
Beneficiary Categories and Which Rules Apply to Each
For deaths after 2019, beneficiary category determines inherited IRA withdrawal options.
| Beneficiary category | General treatment |
|---|---|
| Spouse | May keep the IRA inherited or treat it as their own. |
| Non-spouse, non-EDB individual | Generally subject to the 10-year rule; annual RMDs may apply. |
| EDB | Life expectancy distributions may be available. |
| Estate, entity, or trust | Treatment varies; qualifying trusts may use beneficiary-based rules. |
The 10-Year Rule Explained for Non-Spouse Beneficiaries
- Most non-spouse beneficiaries inheriting after 2019 are subject to the 10-year rule.
- The inherited IRA must be emptied by December 31 of the tenth year after death.
Annual RMDs depend on when the owner died:
- On or after their required beginning date, the deadline for their first RMD: annual RMDs also apply.
- Before that date: annual withdrawals generally aren't required before the final year.
Spousal Beneficiary Options and How the Calculation Differs
A surviving spouse can roll inherited funds into their own IRA or elect to treat the IRA as their own. RMDs then follow owner rules, generally using the Uniform Lifetime Table.
Keeping an inherited IRA can allow life expectancy distributions using Table I, the Single Life Expectancy Table. This method uses the spouse’s current age annually. The choice affects when withdrawals begin and how required amounts are calculated.
The IRS Inherited IRA RMD Table (Single Life Expectancy Table)
For many non-spouse beneficiaries taking life expectancy distributions, IRS beneficiary table guidance uses this sequence:
- The starting factor comes from Table I of Publication 590-B, using the beneficiary’s age the year after death.
- The prior December 31 balance is divided by the applicable factor.
- The starting factor decreases by one each subsequent year.
Accounts That Inherited Before 2020
For original beneficiaries whose IRA owner died before 2020, pre-SECURE Act rules generally allow continued life expectancy distributions without a 10-year deadline. Successor beneficiaries can face different rules.
Eligible Designated Beneficiaries and the Stretch IRA Exception
Eligible designated beneficiaries (EDBs) are a defined group of heirs that the SECURE Act generally exempts from the 10-year rule. Eligible designated beneficiaries may qualify for inherited IRA distributions over life expectancy. The IRS recognizes five categories:
- Surviving spouses.
- The original owner’s minor children.
- Individuals meeting IRS disability criteria.
- Individuals meeting IRS chronic illness criteria.
- People no more than 10 years younger than the owner.
For the owner’s child, the 10-year withdrawal window begins at age 21.
Other qualifying non-spouse beneficiaries generally use the Single Life Expectancy Table.
What Happens When a Beneficiary Misses an Inherited IRA RMD Deadline
- Inherited IRA annual RMDs are generally due December 31.
- For affected beneficiaries under the 10-year rule, the IRS final regulations apply to annual RMDs for 2025 and later years.
Missed RMD excise taxes are:
- 25% of the shortfall.
- 10% if corrected within the applicable correction window.
The tax applies only to the missed amount. Beneficiaries report shortfalls on Form 5329 and can request a reasonable-error waiver under the IRS penalty waiver instructions.
Inherited IRA RMDs and Federal Income Tax
Traditional inherited IRA withdrawals generally count as gross income and are taxed as ordinary income in the year taken. Qualified inherited Roth IRA distributions are tax-free, though many non-spouse beneficiaries still face withdrawal deadlines.
{{blog-cta-financial}}
How Elayne Helps Beneficiaries Stay on Top of Inherited IRA Obligations
Elayne tracks inherited IRA distribution deadlines and surfaces account-specific requirements. Separately, Elayne supports estate organization and asset searches for deceased family members.
A shared dashboard lets authorized family members, attorneys, and financial advisors review deadline status together. Elayne supports tracking and coordination; beneficiaries and their account custodians remain responsible for distributions.
What Elayne tracks for inherited IRAs
Elayne tracks the distribution deadlines and required minimum distributions that apply to inherited retirement accounts under SECURE Act 2.0. For an inherited IRA, that includes the 10-year deadline and annual RMDs where they apply. Elayne also surfaces the 25% excise tax on a missed distribution and the reduced 10% rate when a shortfall is corrected within the allowed window.
Elayne also uses document analysis on tax returns, bank statements, and other financial records. This can surface retirement distributions and the financial institutions connected to them.
Tracking for each inherited account covers:
- The deadline attached to the account.
- Whether annual RMDs apply alongside the 10-year deadline.
- Reminders as each deadline approaches.
- A shared status view for everyone with authorized access.
Who has authority to act on an inherited IRA
Authority over an inherited IRA depends on who is named as beneficiary and what role each person holds.
| Role | Authority over the inherited IRA |
|---|---|
| Named individual beneficiary | Holds the inherited IRA and directs withdrawals with the account custodian. |
| Executor or personal representative | Acts for the estate under court-issued authority documents when the estate is the beneficiary. |
| Trustee | Acts for a trust named as beneficiary, under the terms of the trust. |
| Account custodian | Holds the account, processes distributions, and issues tax reporting forms such as Form 1099-R. |
| Attorney or financial advisor | Assists as authorized by the person who holds authority over the account. |
FAQ
What is an inherited IRA RMD?
An inherited IRA RMD is the minimum amount a beneficiary is required to withdraw from an inherited IRA in a given year. Whether annual RMDs apply depends on the beneficiary's category, the date of death, and whether the owner had reached their required beginning date.
Who acts when an estate or trust is the beneficiary?
When the estate is the beneficiary, the executor or personal representative acts for the estate under court-issued authority documents. When a trust is the beneficiary, the trustee acts under the terms of the trust.
What is the 10-year rule for inherited IRAs?
Many non-spouse beneficiaries who inherit after 2019 are subject to the 10-year rule. The inherited IRA must be emptied by December 31 of the tenth year after the owner's death. Withdrawals larger than the annual minimum are permitted.
Do annual RMDs apply during the 10-year period?
It depends on when the owner died. If the owner died on or after their required beginning date, annual RMDs also apply during the 10 years. If the owner died before that date, annual withdrawals generally are not required before the final year. The IRS final regulations apply to annual RMDs for 2025 and later years.
Who is an eligible designated beneficiary?
Eligible designated beneficiaries are a defined group of heirs that the SECURE Act generally exempts from the 10-year rule. They may qualify for distributions over life expectancy. The IRS recognizes five categories:
- Surviving spouses.
- The original owner's minor children.
- Individuals meeting IRS disability criteria.
- Individuals meeting IRS chronic illness criteria.
- People no more than 10 years younger than the owner.
For the owner's child, the 10-year window begins at age 21.
How do the rules differ for a surviving spouse?
A surviving spouse can roll inherited funds into their own IRA or elect to treat the IRA as their own. RMDs then follow owner rules, generally using the Uniform Lifetime Table. A spouse who keeps the account as an inherited IRA can take life expectancy distributions using Table I, the Single Life Expectancy Table, based on the spouse's current age each year.
How is an inherited IRA RMD calculated with the Single Life Expectancy Table?
The prior December 31 account balance is divided by the applicable IRS factor. For many non-spouse beneficiaries, the starting factor comes from Table I of IRS Publication 590-B, using the beneficiary's age in the year after the owner's death. The factor then decreases by one each subsequent year.
As an example, a $300,000 balance divided by a factor of 30.0 produces an RMD of $10,000.
*Disclaimer: This article is for informational purposes only and does not provide legal, medical, financial, or tax advice. Please consult with a licensed professional to address your specific situation.