Key Takeaways
- The deceased person's estate is responsible for final utility bills, with executors paying these debts from estate funds before distributing assets to heirs
- Surviving family members are not personally liable for deceased persons' utility bills unless they were joint account holders or continue receiving service after death
- Utilities should be transferred to survivors' names or cancelled promptly after death to prevent ongoing charges becoming the responsibility of whoever uses the service
- Some states allow utility companies to place liens on property for unpaid bills, potentially affecting real estate sales or transfers during estate settlement
- Executors must balance continuing necessary utilities to protect vacant property against accumulating unnecessary charges for services that aren't needed during estate administration
{{blog-cta-financial}}
Understanding Legal Responsibility for Estate Debts
A utility service agreement is a contract between the customer and the provider. UNC School of Government guidance explains that, for North Carolina local-government utilities, this contract ends at death. Without a surviving co-account holder, later charges generally cannot be collected unless a survivor or authorized estate representative lawfully opens a new account. Rules elsewhere depend on state law and service terms.
Valid pre-death charges remain estate claims, payable under state creditor priority rules before heirs receive money or real estate. Under the North Carolina guidance, receiving bills alone, without using the service or opening a new account, does not create liability. Actively continuing service is a separate issue; responsibility depends on account agreements and applicable law.
Utilities may learn of a death through direct notification, returned bills, or public notices. Verification and account changes follow the provider's procedures.
Family members are not personally responsible for deceased relatives' debts simply because of their relationship. Adult children do not inherit their parents' utility bills, siblings aren't liable for each other's debts, and other relatives have no obligation to pay from personal funds unless they are liable as joint account holders, guarantors, or surviving spouses under applicable community property laws. Responsibility depends on account agreements and applicable state law.
Exceptions to this protection exist in specific situations that create personal liability. Joint account holders who signed utility accounts alongside the deceased person are fully liable for the entire debt regardless of who actually used the service. Surviving spouses in community property states may be responsible for debts incurred during marriage as community obligations. Anyone who continues receiving utility service after death by keeping accounts active in the deceased person's name accepts responsibility for ongoing charges even if they weren't originally on the account.
Pre-death utility bills generally rank with other unsecured debts unless state law grants special priority or lien rights. Mortgage and property tax payments often receive early attention to prevent foreclosure or tax liens, while homeowners insurance premiums maintain coverage to protect estate assets. Medical bills are generally unsecured, though state law may give final-illness expenses higher priority. Necessary ongoing utilities may qualify as estate administration expenses; payment decisions still follow state creditor priorities, including when funds are limited.
The Consumer Financial Protection Bureau explains that debt collectors cannot use deceptive practices to make relatives pay debts they do not owe. Scam warning signs for bereaved families include callers demanding immediate phone payment "to avoid service shutoff" or "to protect credit." Requests for gift cards or wire transfers, or claims of authority without written account verification, are further red flags. Verifying the collector's identity through independently obtained contact details, requesting written validation of the debt, and consulting the executor or an attorney before any payment on the deceased person's utility account can help prevent fraudulent payments.
How to Notify Utility Companies of a Death: Step-by-Step
- The initial call is made. Any family member, friend, or executor can generally report the death through the provider's customer service or bereavement team. The caller need not be legal next of kin, though reporting a death does not grant authority to change the account.
- Account details and documents are gathered. The caller has the account number, service location, date of death, and available death certificate ready. Some providers require a certified copy. Proof of relationship or court-issued appointment papers may be needed, depending on the requested change.
- The provider verifies the death. Methods vary. North Carolina utility guidance describes confirmation through family, an obituary, or Register of Deeds death records. Public-record access differs elsewhere, and providers may request a certified death certificate instead.
- Any temporary hold is confirmed. The caller asks whether the account can be placed on a bereavement hold and payment requests delayed. A hold or account freeze is not automatic and does not necessarily stop charges. Notification alone does not necessarily trigger immediate shutoff; disconnection protections and deadlines vary.
- Continued service or cancellation is requested. For an occupied home, the survivor requests transfer or new service in their name. For estate property, the authorized executor discusses an estate account. If service is unnecessary, the representative requests cancellation and confirms the effective end date and any access requirements.
- The outcome is documented. Written confirmation records the account arrangement, any hold deadline, final service date, and final-bill instructions. The executor retains the reference number and correspondence, then reviews the final bill and any deposit refund for estate accounting.
Who Is Considered Personally Liable for Utility Bills
Personal liability for a deceased person's utility bills depends on the survivor's legal relationship to the account and actions after death, not simply a family relationship to the deceased.
If one joint account holder dies owing $500 in utility bills, the surviving joint holder must pay the full amount from personal funds if estate assets are insufficient.
For example, a Texas husband and wife share a home, but only his name appears on the electric account. He dies owing $300 for electricity used during their marriage. His wife may be responsible for that $300 despite never being on the account, subject to Texas marital-property liability rules, including whether the electricity qualifies as a household necessity; marriage alone does not create personal liability.
People who continue receiving service after death without notifying utilities or transferring accounts may be liable for ongoing charges. For example, a survivor living in the deceased person's home may receive electric, gas, and water service still billed in the deceased person's name. Responsibility for those charges depends on account agreements, occupancy, and state law.
Executors and administrators are not personally liable for estate debts when acting in their official capacity and properly administering the estate. An executor who pays utility bills from estate funds according to proper procedures is not personally responsible solely because estate assets are insufficient to pay everything owed. However, executors who pay debts in the wrong priority order or distribute estate assets before paying legitimate creditors can become personally liable for unpaid debts to the extent of improper distributions.
Guarantors or cosigners on utility accounts when service was set up bear personal liability separate from their role as family members. Some utility companies require guarantors with good credit to guarantee payment for customers with poor credit history. A person who guaranteed the deceased person's utility accounts can be liable under that agreement for unpaid amounts regardless of whether they lived at the property or used the service.
How to Handle Utilities for Properties Survivors Will Occupy
When surviving family members continue living in the deceased person's home, utilities must be transferred to avoid personal liability for charges accumulating under the deceased person's name.
When arranging continued service, executors and survivors notify utility providers and the deceased person's bank, checking statements for utility direct debits or autopay. Banks typically freeze solely owned accounts and stop automatic payments once notified of the death; joint-account treatment varies. Utility charges may continue even when payments stop.
Arranging new payment methods with providers during account transfers helps prevent service interruptions and missed final bills. Valid estate bills are paid with authorized funds from an estate account, and survivors' ongoing service is paid through their own accounts.
The initial caller need not be next of kin or the executor: a family member, friend, tenant, or representative acting for the family can report the death and request a pause in payment demands. Provider bereavement procedures may allow a temporary collection hold before estate settlement, but a hold is not automatic or universal.
Closing or transferring accounts generally requires documentation, such as a death certificate and proof of authority. Executor appointment papers support changes on the estate's behalf; identification and proof of residency support a survivor's request for new service. Requirements, deposits, and credit checks vary by provider.
The utility closes the deceased person's account with a final bill and opens a new account for the survivor's ongoing service. Responsibility for the final bill depends on existing account obligations and state law.
For example, a surviving adult child with no prior payment obligation opens a new account and pays for service from its start date. The estate owes valid final charges on the deceased person's account, subject to applicable state law.
The final bill and new account separate the estate's obligation from the child's ongoing service charges.
Final bills for service through the date of death remain estate debts even when accounts are transferred to survivors. The company sends the final bill to the estate or the last known mailing location. The executor pays valid claims from estate funds under applicable creditor priority rules. Survivors continuing to live in the property can share the final bill with the executor for payment from estate assets.
Deposit refunds from the deceased person's solely owned accounts belong to the estate, not to survivors who open new accounts. If the deceased person paid deposits to utility companies when setting up service, those deposits plus any accrued interest belong to the estate upon account closure. Deposits might be applied against final bills if balances are owed, or refunded to the estate if the final bill is less than the deposit. These estate-owned refunds are separate from any new deposits required for survivors' accounts.
Some utilities allow account transfers without full credit checks for immediate family members continuing service at the same property. Simplified transfer procedures may be available for surviving spouses or children remaining in the home. These accommodations recognize that the person already lived at the property and continuing service doesn't represent new risk to the utility company.
How to Handle Utilities for Vacant Properties During Estate Administration
This table is a general starting point; decisions depend on property occupancy status and any homeowners association (HOA) or lender requirements.
| Services Usually Kept Active | Services Usually Canceled or Reduced |
|---|---|
| Electric - powers lighting, alarms, and necessary equipment. | Cable/satellite TV - usually unnecessary in an empty home. |
| Heat - helps prevent frozen pipes; settings depend on climate and insurer requirements. | Premium internet packages - basic service may meet security-system needs. |
| Water - retained where plumbing or property systems require it; winterization may change the arrangement. | Landline phone - unnecessary unless alarms or safety equipment depend on it. |
| Security/internet - supports alarms, cameras, and remote monitoring. | Lawn/pool services - reduced or canceled if not needed for marketing, safety, or HOA compliance. |
| Property insurance - maintained with appropriate vacancy coverage. | Newspaper and optional subscriptions - cancellation prevents charges for unused services. |
Heating, cooling, and water arrangements depend on climate, plumbing, and insurer requirements. Reduced settings can limit costs while protecting the home; timed lighting can support security. Vacancy may require an insurance policy change, so continued premium payments alone do not confirm coverage.
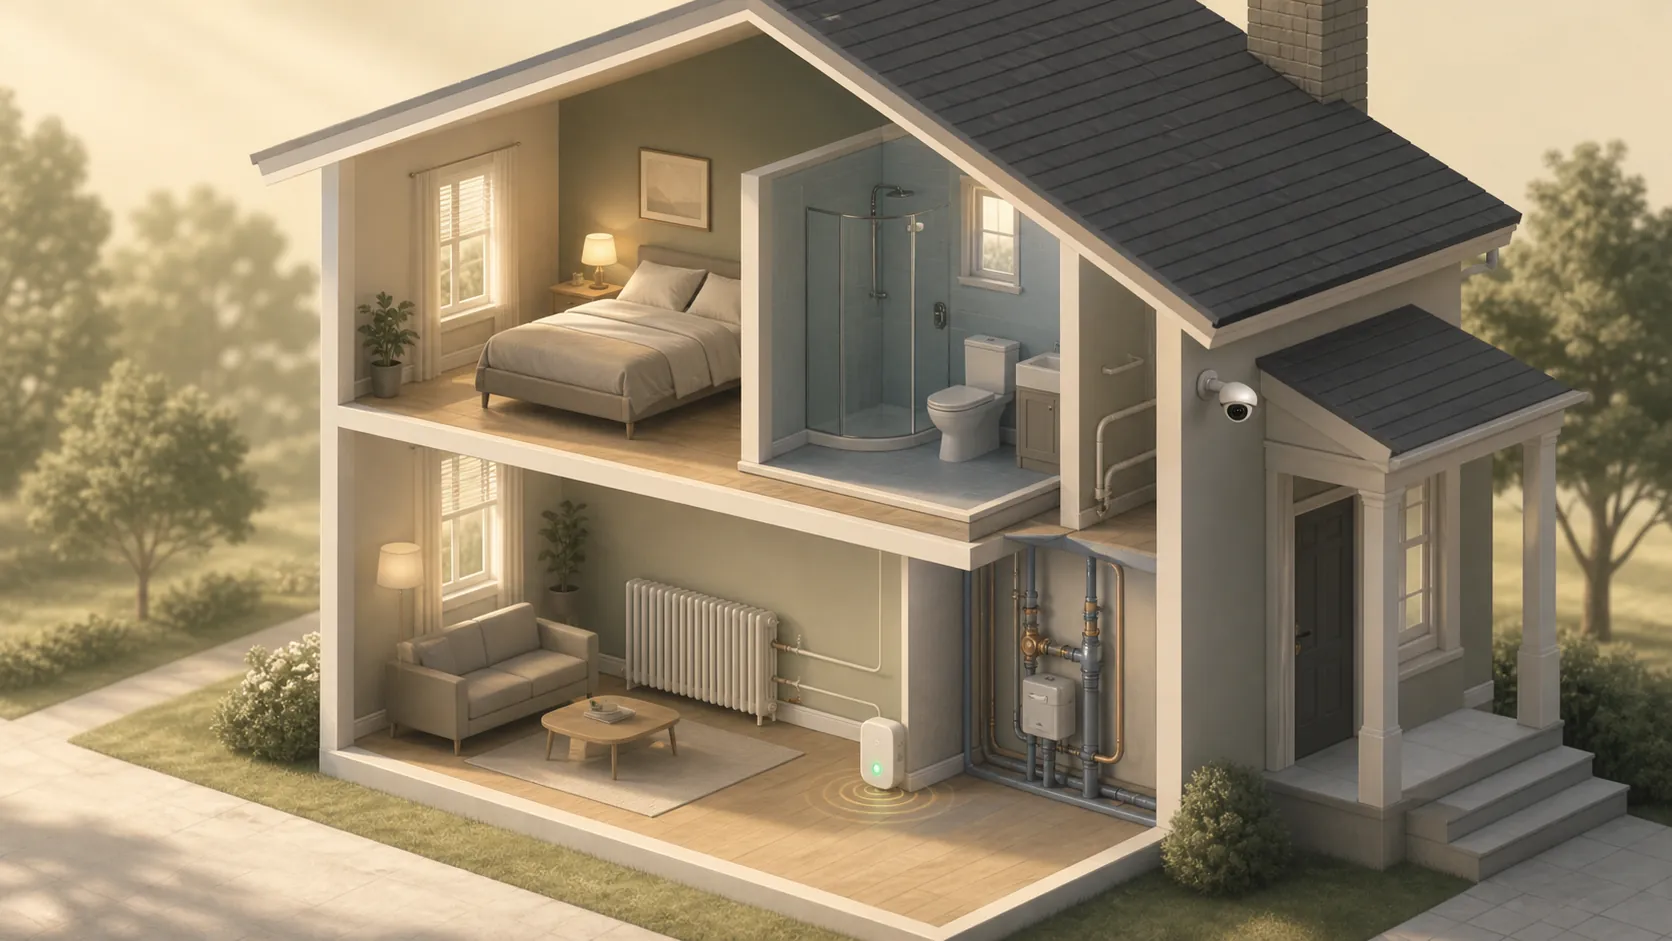
Necessary utilities for vacant estate properties are paid from estate funds as estate administration expenses, subject to payment priorities. After an account closes, final bills, payment confirmations, deposit refund records, and closure correspondence remain in the estate accounting file; Block & Scarpa's general recordkeeping guidance suggests a 3-7 year retention range after the estate closes as one resource's general guidance, not a universal legal requirement; state rules vary. Longer retention may be needed under applicable rules or for unresolved creditor disputes, tax questions, or beneficiary accounting requests. Paperwork retention is separate from how long utility service stays active, which depends on occupancy, property protection needs, and the sale timeline.
Monitoring utility usage helps detect problems like water leaks, HVAC malfunctions, or unauthorized access. Unusual spikes in water consumption might indicate leaks requiring immediate attention before they cause extensive damage. Unexpected electricity increases could signal HVAC problems or unauthorized access. Many utilities provide online access to daily or weekly usage data that helps executors identify problems quickly.
Smart home devices can help monitor and control vacant property utilities remotely if the estate will remain open for many months. Smart thermostats allow adjusting temperature settings from anywhere, smart water sensors detect leaks and send alerts, smart locks allow controlled access for real estate agents or contractors without physical keys, and smart lights can be controlled remotely for showings or to simulate occupancy. Whether these devices are worth the cost depends on purchase and installation costs, any subscription fees, and how long the property will remain vacant; savings are not guaranteed.
State Laws About Utility Debt Collection and Property Liens
Understanding how the applicable state allows utility companies to collect unpaid bills and whether they can place liens on property helps executors rank utility payments appropriately among competing creditor claims.
Some states grant utility companies special lien rights against real property for unpaid bills that survive account holder death and transfer with the property. These utility liens attach to the property itself, meaning new owners inherit the obligation to pay outstanding utility debts before the property can be sold with clear title. Pennsylvania and New Jersey, for example, allow liens for certain municipal water and sewer charges, though rules vary regarding eligible providers, covered charges, and lien enforcement procedures.
Utility liens can complicate estate property sales because title companies require liens to be paid before closing. When conducting title searches in preparation for real estate sales, unpaid utility bills with filed liens appear as title defects that must be resolved. Buyers and their lenders typically require clear title with no outstanding liens, forcing estates to pay the utility debts regardless of whether sufficient estate assets exist to pay all creditors.
Priority rules for utility debts compared to other estate obligations vary by state. Some states classify utility bills as priority debts that must be paid before general unsecured creditors, including companies collecting credit card debt. Other states treat utilities as ordinary unsecured debts with no special priority.
Any special priority may depend on when the service was provided, under the applicable state statute. Understanding priority rules helps executors properly allocate limited estate funds when assets are insufficient to pay all creditors.
The statute of limitations for collecting utility debts varies by state and the type of claim; the applicable deadline requires verification under that state's law. After the limitations period expires, utility companies generally cannot sue to collect unpaid bills though the debt technically still exists. However, utility liens filed before limitations expire can remain attached to property indefinitely until paid. Executors should be aware of limitations periods when deciding whether to pay older utility bills from limited estate funds.
New occupants generally do not owe a previous occupant's utility debt solely because they move into the property. Service eligibility depends on applicable state and local rules, provider terms, and any property-based charges or liens. A new owner may also face deposit or advance-payment requirements based on credit history.
Consumer protection laws restrict utility companies' collection practices for debts owed by deceased persons. Companies must follow applicable utility rules, cannot misrepresent family members' liability, and must provide accurate final billing and process account closures under applicable requirements. Complaints about improper collection practices can be submitted to the state public utility commission or other authority that oversees the provider.
Practical Steps for Executors Handling Utility Bills
Systematically managing utility accounts, bills, and payments during estate administration helps protect properties, limit costs, and maintain proper accounting for beneficiary and court review.
Executors prepare a detailed list of all utility and service accounts early in estate administration. They request final account statements from each utility provider identified through mail, bank statements, or property records. The list records account numbers, monthly costs, service locations, and contact information for each provider. This inventory helps prevent overlooked services from continuing to charge while other estate matters are being handled.
Decisions to continue, reduce, or cancel each utility depend on property circumstances. Properties occupied by survivors generally need account transfers, while vacant properties being prepared for sale need necessary utilities maintained at appropriate levels. Properties being distributed to beneficiaries who will immediately occupy them might need utilities kept at normal levels. Properties slated for demolition or left vacant may need disconnection arrangements that follow provider and local safety requirements.
Executors can notify utility companies of a death while decisions about continued service are still pending. Notification starts the provider's closure or transfer process; charges depend on the effective service end date. Written notifications sent by certified mail provide proof of the notification date for estate records.
Executors request final bills when notifying utilities of a death. The request identifies the proposed final service date, subject to provider procedures and applicable law. Clear final billing separates the deceased person's account obligations from subsequent service that survivors might receive. Final bills help document estate obligations and charges that may belong to someone else.
Executors pay valid final utility bills from estate funds according to applicable creditor deadlines and payment priorities. Pre-death charges are estate debts; necessary post-death service for estate property may qualify as an administration expense. Timely payment under those rules can limit late fees and potential liens while preserving funds for higher-priority obligations.
All utility payments are recorded carefully as part of estate accounting. Records include copies of final bills, payment confirmations, and any correspondence with utility companies. This documentation supports estate accounting that beneficiaries and courts may review. Clear records show that the executor properly managed estate assets and paid legitimate debts before distributions.

Executors may discuss settlements with utility companies if estate assets are insufficient to pay all creditor claims, including utilities. Some companies will accept partial payment settlements for unpaid accounts when the alternative is receiving nothing through probate proceedings. These discussions include the estate's financial situation, documentation of assets and liabilities, and proposed payment amounts consistent with creditor priority rules. Not all companies will negotiate, but settlement might reduce estate obligations.
When Estate Assets Cannot Pay All Utility Bills
Insolvent estates where debts exceed assets create challenges for executors who must properly allocate limited funds among competing creditor claims including unpaid utility bills.
Priority rules set by state law determine the order in which executors must pay different types of debts when estate assets are insufficient to pay everything owed. Priority categories can include estate administration expenses, funeral expenses, taxes, medical expenses from the final illness, and other debts; their order depends on applicable law. The state's priority scheme determines whether utility bills are paid before or after other creditors.
Executors must follow statutory priority rules when paying debts from insufficient estate assets or face potential personal liability for preferential payments. Paying low-priority creditors before higher-priority creditors are satisfied can expose an executor to claims for improper payments. Following the applicable priority rules helps protect executors from personal liability.
Pro rata distribution divides available funds proportionally among creditors in the same priority class when permitted by applicable law. In this hypothetical example, higher-priority claims have already been handled and $5,000 remains for a class with $10,000 in valid claims.
| Creditor group | Valid claims | Share paid | Payment |
|---|---|---|---|
| Utilities | $3,000 | 50% | $1,500 |
| Other creditors in the same class | $7,000 | 50% | $3,500 |
Each creditor in this example receives half of the valid claim, instead of the first creditor receiving full payment.
Communicating with utility companies about estate insolvency can prevent misunderstandings and potentially lead to debt forgiveness. Executors can document the estate's financial situation and discuss whether the provider accepts partial payment or forgives an uncollectible balance. Some companies have policies for writing off uncollectible deceased-account balances instead of continuing collection efforts.
Family members generally have no obligation to pay utility bills from personal funds when an estate is insolvent unless a separate legal obligation makes them liable. Voluntary payment uses personal funds for a debt that may belong solely to the estate. Unpaid estate debts do not become family members' personal obligations merely because estate funds run out.
Insolvent deceased persons' estates generally proceed under state probate and creditor-payment rules. A probate attorney can explain the applicable insolvency procedures when substantial assets or creditor disputes are involved.
FAQ
How are recurring charges and subscriptions stopped after a spouse dies?
Stopping unwanted recurring charges involves canceling the service with the provider and arranging for automatic payments to end. A surviving spouse or authorized estate representative identifies subscriptions in available bank and credit card statements, then requests cancellation through each provider's bereavement or customer service process. Providers may require a death certificate and proof of authority; being a spouse does not automatically grant access to a solely owned account.
The CFPB's automatic-payment guidance explains that stopping bank debits does not cancel a service contract or erase amounts owed. The authorized representative confirms payment arrangements with the bank or card issuer, keeps written cancellation confirmations, and reviews later statements for charges after the cancellation date. Unused streaming, gym, or app subscriptions can be handled separately from utilities needed to keep an occupied or vacant home safe.
Who pays utility bills after someone dies?
The estate pays valid final utility bills from estate funds under state creditor priority rules. Survivors pay for their own ongoing service, and joint account holders or others with a separate legal obligation may owe existing charges personally. Family relationship alone does not create liability.
How long should utility bills be kept after a death for records?
The Block & Scarpa guidance cited earlier suggests keeping estate records for 3-7 years after the estate closes, but there is no single retention period for every estate. Final bills, payment confirmations, and provider correspondence stay in the estate accounting file for the period required by applicable probate and tax rules, taking unresolved claims into account. An estate attorney or tax professional can clarify whether longer retention is needed.
Can utility companies turn off service immediately after notification of death?
Reporting a death does not necessarily trigger immediate shutoff. Disconnection protections, notice requirements, and service deadlines depend on state law and provider procedures. Continued service or a temporary hold requires confirmation with the provider; a hold does not necessarily stop charges.
What happens if no one pays the final utility bill?
The provider may pursue a valid estate claim, and unpaid charges may lead to collection efforts or a lien where law permits. If estate funds are insufficient, state payment priorities govern what creditors receive. An unpaid estate balance does not become a relative's personal debt solely because estate funds run out.
Can a utility company put a lien on the house for unpaid bills?
Some states permit property liens for certain utility charges, including municipal water or sewer bills. Eligible providers, covered charges, and enforcement rules vary by state. A valid lien may need to be resolved from estate funds or sale proceeds before clear title can pass.
Does an executor need to pay the deceased person's utility bill from personal funds?
Serving as executor alone does not require personal payment of estate utility bills. Personal liability may arise from a joint account, guarantee, or another obligation under state law. Improper estate payments or distributions can also create liability; valid estate bills are paid with estate funds under applicable priority rules.
Next Steps for Executors Managing Utility Bills
Executors begin by notifying utility providers promptly, gathering account details and proof of authority, and confirming whether anyone will remain in the property. Occupied homes generally need service transferred to a survivor or a new account opened, with the start date confirmed. Vacant homes may need heating, electricity, or water to protect properties, depending on climate, plumbing, and insurer requirements. Unneeded accounts are canceled with written confirmation of the service end date; notification alone does not necessarily stop charges.
Valid final bills are paid from estate funds in the creditor priority order required by state law, before distributions to heirs. Final statements, payment confirmations, deposit refunds, and transfer or cancellation correspondence remain in the estate accounting file. Family relationship alone does not create personal liability, though joint holders, co-signers, and survivors continuing service without transferring an account may owe charges under applicable agreements and law. Executors can consult an estate attorney or probate professional if state-specific lien laws or community property rules leave payment responsibility uncertain.
{{blog-cta-financial}}
This content is for informational purposes only and does not constitute legal, financial, medical, or tax advice. Laws and regulations vary by state and individual circumstances differ. Consult a licensed attorney, financial advisor, or other qualified professional for guidance specific to your situation.